By the HomeAffordLab team · Last updated October 27, 2026
At today’s average 30-year mortgage rate of about 7.3%, a household earning $90,000 a year with $500 in monthly debt payments and $25,000 saved for a down payment can comfortably afford a home of about $255,000. That keeps the full monthly payment, including taxes, insurance, and PMI, near $2,100. A lender may approve up to about $351,000, but that stretch budget leaves little room for anything else.
As a quick rule, with 10% down and no other debt, most buyers can comfortably afford about 2.7 to 3 times their gross annual income at current rates. This guide is for first-time buyers who want their real number before talking to a lender. Use the calculator below with your own figures, then read on to see what moves the result most.
Key takeaways
- The 28/36 rule caps housing costs at 28% of gross monthly income and all debt payments at 36%.
- Your monthly payment is more than principal and interest. Taxes, insurance, and mortgage insurance often add 25% or more.
- On a $90,000 income, debt payments above $600 a month start shrinking your budget. At $1,000 a month, your comfortable price falls by about $49,000.
- A 1-point drop in your rate adds about $20,000 to your comfortable price on a $90,000 income.
- Lenders can approve you for far more than is comfortable. Decide your own limit first.
In this guide: How the calculator works · The 28/36 rule · Affordability by salary · A worked example · Comfortable vs. lender limits · What changes your number · Hidden costs · How to afford more, safely · FAQ
How Much House Can I Afford? Calculator
Includes property tax, homeowners insurance, PMI or FHA mortgage insurance, and HOA dues.
How the home affordability calculator works
The calculator works backward from your income. First, it finds the largest monthly housing payment your income and debts allow. Then it searches for the home price whose full payment fits inside that limit.
That full payment is often called PITI: principal, interest, taxes, and insurance. Our mortgage affordability calculator also adds the costs most free tools leave out:
- Property tax, set at 1.0% of the home’s value per year by default. The national average effective rate is about 1.01%, according to the Tax Foundation’s 2026 analysis of U.S. Census data.
- Homeowners insurance, set at $2,450 per year. Bankrate puts the national average at $2,424 for a policy with $300,000 of dwelling coverage.
- Private mortgage insurance (PMI) on conventional loans with less than 20% down, set at 0.5% of the loan per year.
- FHA mortgage insurance, which includes a 1.75% upfront premium added to the loan and an annual premium of 0.55% for most borrowers.
- HOA dues, if the home is in a community association.
You get two answers. Comfortable follows the 28/36 rule. Stretch uses the debt-to-income limits lenders commonly apply. The gap between them shows how much risk you would take on by borrowing the maximum.
The 28/36 rule, explained
The 28/36 rule is the most widely used guideline for how much mortgage you can afford. It has two parts:
- Front-end ratio (28%): your total monthly housing cost should be no more than 28% of your gross monthly income.
- Back-end ratio (36%): your housing cost plus all other monthly debt payments should be no more than 36% of your gross monthly income.
The lower of the two limits sets your budget. On a $90,000 income, gross monthly income is $7,500. The front-end limit is $2,100 (28% of $7,500). The back-end limit is $2,700 (36%), minus $500 of existing debt, which leaves $2,200 for housing. Your budget is the smaller figure: $2,100 a month.
If you carry heavy debt, the back-end ratio usually decides. If you carry little or none, the front-end ratio does. That is why paying off a car loan can raise your budget, but only up to the point where the 28% cap takes over.
How much house can I afford on my salary?
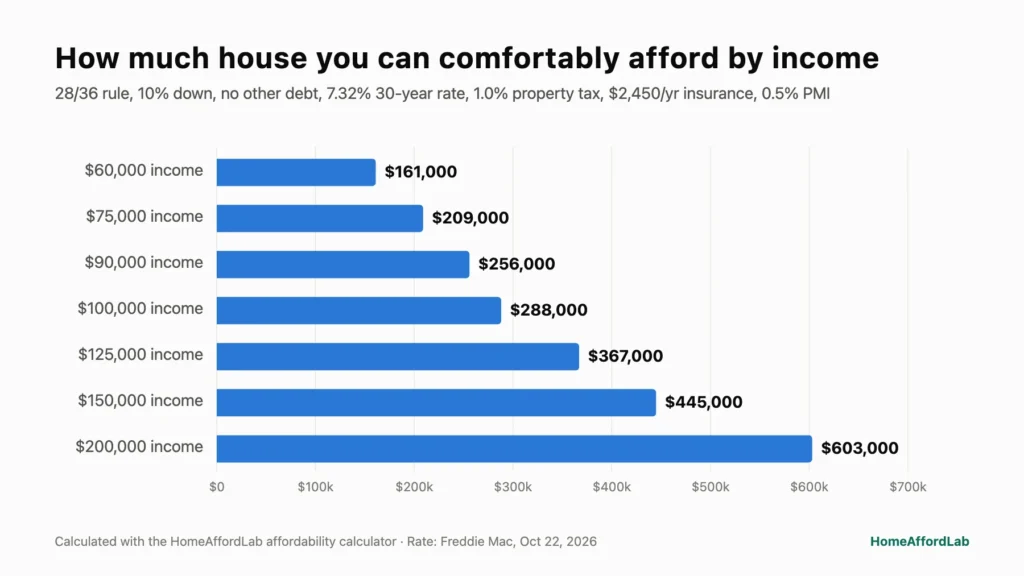
The table shows the comfortable home price at different incomes. It assumes 10% down, no other debt, a 7.32% rate on a 30-year conventional loan, 1.0% property tax, $2,450 a year in insurance, and 0.5% PMI.
| Gross annual income | Comfortable home price | Down payment (10%) | Monthly payment |
|---|---|---|---|
| $60,000 | $161,000 | $16,100 | $1,400 |
| $75,000 | $209,000 | $20,900 | $1,750 |
| $90,000 | $256,000 | $25,600 | $2,100 |
| $100,000 | $288,000 | $28,800 | $2,333 |
| $125,000 | $367,000 | $36,700 | $2,917 |
| $150,000 | $445,000 | $44,500 | $3,500 |
| $200,000 | $603,000 | $60,300 | $4,667 |
The multiple of income rises slightly as income grows, from about 2.7 times at $60,000 to 3 times at $200,000. Insurance is a fixed dollar cost, so it takes a bigger share of smaller budgets.
A worked example: $90,000 income, $25,000 down
Here is how the default scenario in the calculator breaks down.
| Monthly cost | Amount |
|---|---|
| Principal & interest (7.32%, 30 years) | $1,586 |
| Property tax (1.0% per year) | $213 |
| Homeowners insurance | $204 |
| PMI (0.5% per year) | $96 |
| Total monthly payment | $2,100 |
The comfortable home price is about $255,000, with a loan of $230,931 and a 9.8% down payment. Principal and interest make up only 76% of the payment. The other $514 a month is the part most quick online calculators leave out, and it is the reason many buyers get approved for a payment that feels tighter than expected.
At the stretch limit, the same household could borrow enough for a home of about $351,000, with a payment near $2,875. That is 38% of gross income going to housing alone, before groceries, childcare, or savings.
Comfortable budget vs. what lenders will approve
Lenders measure the same ratios, but their limits are higher than the 28/36 rule. They also vary by loan program. Our debt-to-income ratio guide explains how each limit is calculated. Before you shop, get a mortgage preapproval so sellers take your offer seriously.
| Loan type | Typical DTI limits | Minimum down payment | Mortgage insurance |
|---|---|---|---|
| Conventional | 36% standard; up to 45–50% with strong credit, reserves, or automated approval | 3% | PMI, removable at 20% equity |
| FHA | 31% housing / 43% total; higher with compensating factors | 3.5% (credit 580+) | 1.75% upfront + annual MIP |
| VA | 41% total guideline, plus a residual-income test | 0% | None (one-time funding fee instead) |
| USDA | 29% housing / 41% total | 0% | Upfront and annual guarantee fees |
A pre-approval tells you the most a lender will lend. It does not tell you what fits your life. Childcare, retirement savings, and commuting costs never appear in a DTI ratio. Set your own ceiling with the comfortable number, then treat anything above it as a deliberate trade-off.
What changes how much house you can afford
Five inputs move the result far more than the rest. Here is how each one shifts the comfortable price in our $90,000 example. For the full breakdown of minimums and monthly costs, see how much down payment you need.
Your mortgage rate
| 30-year rate | Comfortable home price |
|---|---|
| 6.32% | $276,000 |
| 6.82% | $265,000 |
| 7.32% | $255,000 |
| 7.82% | $246,000 |
Each half-point is worth about $10,000 of buying power. Freddie Mac’s weekly survey put the 30-year average at 7.32% on October 22, 2026, down from 7.40% a week earlier but up from 6.19% a year earlier. Even a quarter-point lower quote from a different lender changes your budget, which is why comparing at least three offers matters.
Property taxes where you buy
Effective property tax rates range from 0.27% in Hawaii to 2.23% in New Jersey, based on Tax Foundation data. Holding everything else equal, that difference moves the comfortable price in our example from $276,000 to $227,000. Always check the county rate, not the state average.
Homeowners insurance
Insurance has become a major affordability factor. Insurance.com data shows Florida homeowners paying an average of $8,471 a year in 2026. At that premium, the comfortable price in our example drops from $255,000 to about $194,000. Get an insurance quote before you make an offer, not after.
Existing debt
The back-end ratio only bites once your debts are large enough. In our example, nothing changes until monthly debt payments pass $600. Above that point, every extra dollar of debt is a dollar less for housing, so paying off a $400 car payment can add tens of thousands to your budget.
Your down payment
A bigger down payment raises your price, but less than most people expect, because the monthly payment limit still applies. Doubling the down payment from $25,000 to $50,000 raises the comfortable price only from $255,000 to about $278,000. The bigger benefit is a smaller loan, lower PMI, and more equity from day one.
Costs the calculator can’t see
The monthly payment is not the whole cost of owning a home. Budget for these before you decide on a price:
- Closing costs: usually 2% to 5% of the price, paid at closing. On a $255,000 home, that is about $5,100 to $12,800.
- Maintenance and repairs: many planners use 1% to 2% of the home’s value per year.
- Utilities: often higher than in an apartment, especially in an older or larger home.
- Emergency fund: aim to keep three to six months of expenses after closing. A water heater or roof repair will not wait.
- Moving and furnishing: easy to forget and rarely cheap.
How to afford more house without overextending
- Pay down high-payment debt first. Clearing a car loan or credit card balance lowers your back-end ratio directly.
- Improve your credit score. A higher score can lower both your rate and your PMI premium. Check your reports for free at AnnualCreditReport.com.
- Compare at least three lenders. The Consumer Financial Protection Bureau recommends requesting Loan Estimates from several lenders and comparing them side by side.
- Look for down payment assistance. Most states run first-time buyer programs with grants or low-interest second loans.
- Consider an FHA or VA loan. FHA accepts lower credit scores and 3.5% down. VA loans need no down payment and no monthly mortgage insurance for eligible veterans and service members.
- Shop property taxes and insurance, not just prices. Two homes at the same price can differ by hundreds of dollars a month.
Frequently asked questions
How much house can I afford on a $100,000 salary?
With 10% down, no other debt, and a 7.3% rate, about $288,000 under the 28/36 rule. That assumes average property taxes and insurance. In a high-tax or high-insurance area, the number can be $30,000 to $60,000 lower.
Is the 28/36 rule still realistic with today’s home prices?
It is conservative by design, and many buyers in expensive markets go above it. The rule’s value is that it leaves room for savings and surprises. If you exceed it, do it knowingly, with a solid emergency fund and stable income.
What credit score do I need to buy a house?
Fannie Mae dropped its 620 minimum for loans approved through its automated underwriting system in November 2025, but many lenders and mortgage insurers still set their own minimum, often around 620. FHA loans allow a 3.5% down payment with a score of 580 or higher, or 10% down with a score from 500 to 579.
How much do I need for a down payment?
As little as 3% on some conventional loans, 3.5% on an FHA loan, and 0% on VA and USDA loans. Putting down less than 20% on a conventional loan means paying PMI. You can ask your servicer to cancel it once you reach 20% equity, and it ends automatically at 22%.
Does a mortgage pre-approval tell me what I can afford?
It tells you what a lender is willing to lend, which is usually more than what is comfortable. Use the calculator’s comfortable number to set your own limit before you shop.
The bottom line
How much house you can afford depends on your income, your debts, and today’s rates, but also on taxes and insurance where you buy. At current rates, a comfortable target is roughly 2.7 to 3 times your gross income with 10% down. Run your own numbers in the calculator above, then compare quotes from at least three lenders to see how much a better rate adds to your budget. Once you have a home in mind, use our mortgage payment calculator to see its full monthly payment and amortization schedule.
Estimates only. HomeAffordLab is not a lender and does not provide financial advice. This page may contain ads. See our Advertising Disclosure.
Sources: Freddie Mac Primary Mortgage Market Survey · HUD Mortgagee Letters 2023-05 and 2025-23 (FHA premiums and 2026 limits) · Tax Foundation, Property Taxes by State and County, 2026 · Bankrate homeowners insurance costs · Consumer Financial Protection Bureau